- Article

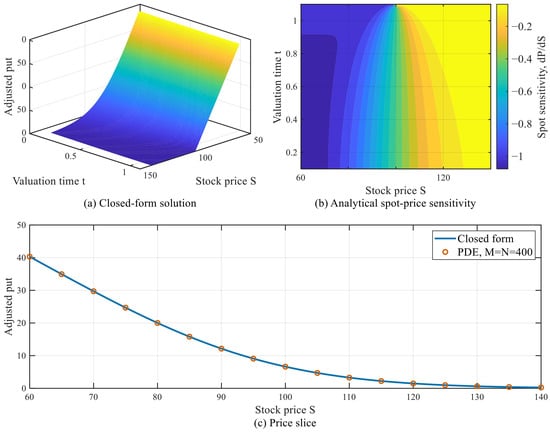
We study a consumption-adjusted fractional Black–Scholes terminal-value equation with deterministic coefficients. An absolutely continuous adjustment yields explicit put and call formulas through cumulative drift, variance, and discount factors. For deterministic time-varying volatility, the variance coefficient retains the historical covariance of the fractional integral. The representation follows a standard Gaussian reduction; the analysis identifies the joint coefficient changes induced by the adjustment and their Brownian limit. Cash and stock consistency tests show that the adjusted operator generally does not preserve the prices of the original market. A deterministic scaling relates its solution to European valuation in an auxiliary diffusion market, without identifying that market with the fractional asset process. Reproducible quadrature and finite-difference experiments verify the formulas, while classical option benchmarks illustrate the distinction from American optimal stopping.
13 November 2026