Skip to Content
You are currently on the new version of our website. Access the old version .
  • 5.5
    CiteScore
  • 19 days
    Submission to First Decision
  • 6 days
    Acceptance to Publication

Journal of Risk and Financial Management

Journal of Risk and Financial Management is an international, peer-reviewed, open access journal on risk and financial management, published monthly online by MDPI (since Volume 6, Issue 1 - 2013).

Get Alerted

Add your email address to receive forthcoming issues of this journal.

All Articles (4,691)

  • Article
  • Open Access

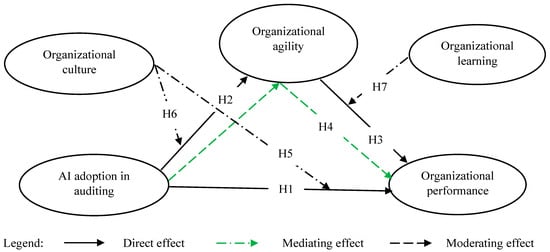
Artificial Intelligence (AI) is rapidly transforming auditing process and methodology by shifting the profession from retrospective sampling to continuous, population-wide assurance and predictive risk management. But little is known about how this technology affects audit firms’ overall performance in emerging economies. This research aims to address these issues by exploring the impact of AI adoption in auditing on performance and the extent to which organizational agility mediates this influence, while organizational culture and learning moderate it. The study collected responses from 226 audit professionals at Big Four audit firms in Ghana through surveys and computer-assisted web interviews using a purposive sampling strategy. The data was analyzed using Partial Least Squares Structural Equation Modelling (PLS-SEM) 4.11.8 in SmartPLS. The findings indicate that AI adoption improves organizational performance and agility. Organizational agility had a positive and significant impact on organizational performance and partially mediated the relationship between AI adoption and organizational performance. Organizational culture had a significant positive moderating impact on the relationship between AI adoption and organizational performance and between AI adoption and organizational agility. Organizational learning significantly and positively moderates the relationship between organizational agility and organizational performance. This study underscores the need for organisations to align strategic AI investments with organizational capabilities to maximize organizational performance in emerging economies.

J. Risk Financ. Manag.

13 November 2026

Conceptual framework. Source: Author’s own work.
  • Article
  • Open Access

Sanctions and the Geography of Recorded Iranian Crude Oil Trade from 2010 to 2020

  • Oswaldo J. Patiño,
  • Nicole A. Soto Sánchez and
  • Paolo J. Aspiazu
  • + 3 authors

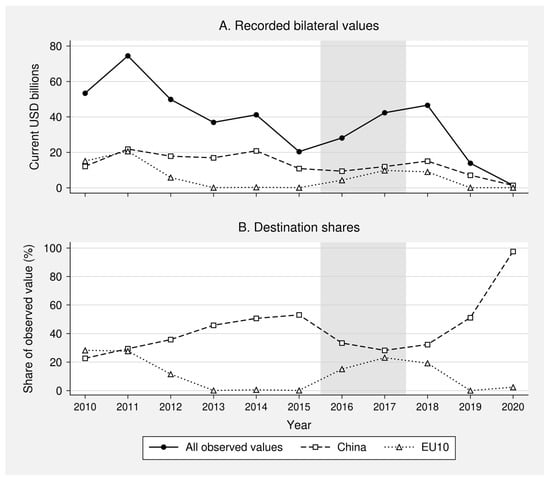
A rising destination share can conceal a falling level of trade. We examine this relationship for Iranian crude oil (HS 2709) during 2010–2020 using importer-side UN Comtrade records for 24 destinations, an independent Turkish regulatory series, and national statistics that help classify absent records. The 109 positive destination-year records are compared in value, destination share, concentration within fixed sets of buyers, net weight, and implied unit value; the 155 absent cells are documented and retained as missing in the principal analysis. Poisson pseudo-maximum likelihood models with destination and year fixed effects interact European destinations with policy periods over 2010–2019, with 2020 treated descriptively. Recorded value fell from USD 74.40 billion in 2011 to USD 13.86 billion in 2019. China’s share rose from 29.3% to 51.1% while its import value fell from USD 21.82 billion to USD 7.08 billion; among four continuously observed Asian buyers, two-thirds of the logarithmic decline in value reflects lower weight rather than lower unit values. The European-to-other-destination ratio was 96% lower in 2013–2015 than in 2010–2011, with consistent evidence across jackknife and wild cluster bootstrap inference and analyses omitting each destination and year in turn. The estimates describe observed positive flows and do not identify causal sanctions effects or show that redirection compensated for lost exports.

J. Risk Financ. Manag.

13 November 2026

Recorded trade values and destination shares. Source: archived UN Comtrade importer-side records and the calculations described in Section 4. Shading identifies 2016–2017. Values are nominal CIF imports; shares are conditional on observed positive records. The concentration in 2020 does not imply complete observation of physical shipments.
  • Article
  • Open Access

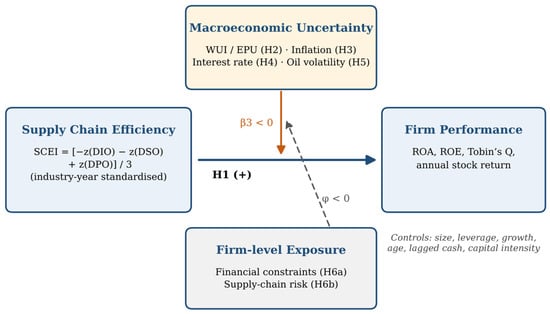
Lean supply chains release capital and support profitability, but they may leave firms exposed when conditions become hard to predict. This study examines whether the financial value of supply-chain efficiency depends on macroeconomic uncertainty, using 182 non-financial firms listed on the Saudi Exchange over 2015–2025 (1622 firm-years). Efficiency is measured by a working-capital-based Supply Chain Efficiency Index (SCEI) built from standardized inventory and receivables periods, and the macroeconomic environment reported by the World Uncertainty Index for Saudi Arabia, global economic policy uncertainty, inflation, interest rates and oil price volatility. Panel models with industry and year fixed effects, system GMM, event studies of the 2014–2016 oil price collapse and the 2020 COVID-19 shock, and multiple-testing corrections are used. Efficiency is positively associated with ROA, ROE and Tobin’s Q, predicts next-year performance and remains significant in GMM estimates, but not in within-firm (firm fixed-effects) models. There is no strong evidence that the efficiency premium weakens when uncertainty, inflation, interest rates or oil price volatility are high, even for the most oil-exposed firms. Some narrowing appears only during the 2020 shock, and efficient firms fell less in both extreme shocks. For financial outcomes, the efficiency–resilience trade-off appears episodic rather than a continuous cost of routine uncertainty.

J. Risk Financ. Manag.

13 November 2026

Conceptual framework. β1 is the direct effect of supply-chain efficiency (H1) and β3 the moderating effect of macroeconomic conditions (H2–H5). The direct effect of the macroeconomic moderators is absorbed by the year fixed effects and is not estimated (Section 3.6.2).
  • Article
  • Open Access

Machine learning is often assumed to be necessary for forecasting equity volatility, yet risk governance increasingly requires models that can be audited. This study asks whether a compact, readable fuzzy rule base can forecast volatility regimes as well as a leading machine learning model, and whether the machine learning advantage reported in one sample holds elsewhere. Three pre-registered studies covering 181 stocks in thirteen markets test these questions against standard volatility benchmarks, with protocols fixed and time-stamped before the test data were analysed. The transparent rule base performed essentially as well as the machine learning model in every study and reproduced the relationship that model had learned. The machine learning advantage over standard benchmarks appeared in the U.S. sample but did not replicate in other markets; market-wide realized volatility helped modestly, whereas lagged implied volatility did not; and using the forecasts to scale exposure did not improve risk-adjusted returns. The findings imply that, for this task, institutions need not trade interpretability for accuracy, and that claims of machine learning superiority in finance should be judged by pre-registered replication across markets before they inform risk-management practice.

J. Risk Financ. Manag.

13 November 2026

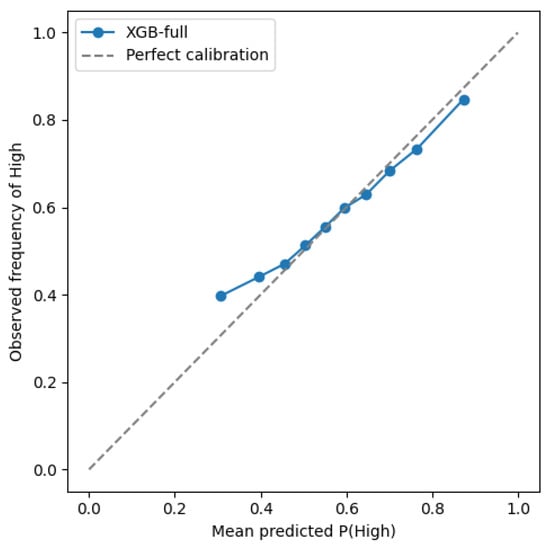
Calibration of XGBoost on the Study 1 test (deciles of predicted probability).

Highly Accessed Articles

News & Conferences

Latest Issues

Open for Submission

Journal Sections

XFacebookLinkedIn
J. Risk Financ. Manag. - ISSN 1911-8074