


Abstract
Digitalisation is increasingly viewed as an instrument for narrowing the VAT gap in the European Union, yet the relative relevance of voluntary business digitalisation and mandatory administrative reporting remains unclear. This study distinguishes cloud accounting from mandatory transaction reporting and analyses an unbalanced EU-27 panel for 2013–2024, with estimations limited to 2013–2023. Sequential pooled OLS, two-way fixed-effects models and robustness checks are applied to European Commission, Eurostat and World Bank data. The initially negative association between cloud accounting and the VAT gap disappears after controlling for income and government effectiveness. Mandatory digital reporting is associated with a VAT gap of about 3–4 percentage points lower, although the small number of adopters and pre-adoption trends preclude causal claims. Theoretically, first, the findings distinguish firm-level digital capability from information directly accessible to tax administrations; second, they show that technology adoption and institutional capacity must be analysed separately. Practically, first, the results support interoperable systems providing timely, structured and verifiable transaction data; second, they indicate that cloud accounting should complement, rather than replace, mandatory reporting infrastructure.
1. Introduction
EU Member States failed to collect about €128 billion of theoretically due VAT in 2023 (European Commission, Directorate-General for Taxation and Customs Union, 2025). This shortfall—the VAT gap—reduces resources for public services, shifts pressure to compliant taxpayers, and advantages firms that conceal or misreport liabilities. Narrowing it therefore remains a central EU tax-policy objective.
Digitalisation is central to this agenda. When embedded in effective administration, digital tools can improve tax-base identification, lower compliance costs, strengthen monitoring, and support targeted enforcement (Okunogbe & Santoro, 2023; Hesami et al., 2024). The VAT in the Digital Age package extends electronic invoicing and digital reporting, but the key empirical question remains which form of digitalisation is most closely associated with a smaller VAT gap.
Digitalisation operates through distinct information channels. Firms voluntarily use cloud accounting to automate records and improve internal reporting, subject to organisational readiness, skills, security perceptions, and external support (Tawfik et al., 2023; Vo Van et al., 2025; Alshenaifi & El Sayad, 2026). Mandatory reporting instead supplies structured transaction data to tax administrations. The first channel improves firm-level information; the second changes the information available for verification.
Country-level reform studies show promising but context-specific results. Mandatory electronic invoicing increased reported sales, purchases, and VAT liabilities in Peru (Bellon et al., 2022, 2023), improved audit targeting and net VAT payments in Rwanda (Kotsogiannis et al., 2025), reduced cross-border VAT fraud in Italy (Heinemann & Stiller, 2025), and increased reported turnover in Hungary (Ván et al., 2025). Differences in institutional setting, coverage, timing, and identification limit EU-wide generalisation. Cloud-accounting studies, meanwhile, focus mainly on adoption and organisational outcomes (Vo Van et al., 2025). The two channels have rarely been assessed separately within a common EU-27 framework, particularly after controlling for income and institutional quality.
This study addresses that gap by comparing voluntary cloud accounting and mandatory digital reporting within a common EU-27 framework. It combines European Commission VAT-gap estimates, Eurostat business-digitalisation indicators, and an author-coded indicator of mandatory digital reporting in an unbalanced panel covering 2013–2024; the main estimations end in 2023 because the 2024 VAT-gap values are preliminary. Sequential models test whether the observed relationships persist after income, tax structure, and government effectiveness are controlled for. The study contributes theoretically by distinguishing internal digital capability from administratively accessible transaction information and empirically by comparing their associations with the VAT gap under a common set of controls.
The remainder of the paper is organised as follows. Section 2 reviews VAT collection, the EU regulatory context, institutional determinants, cloud accounting, and mandatory reporting, and develops the three hypotheses. Section 3 describes the data, variable coding, software environment, and empirical equations. Section 4 presents the descriptive, convergence, and regression results. Section 5 discusses the scholarly and policy implications, limitations, and future research. Section 6 concludes the study.
2. Literature Review and Hypotheses
2.1. VAT Collection, Tax Compliance Theory, Third-Party Information, and Digital Control
VAT is collected through a chain of taxable sales and deductible purchases. A registered seller charges output VAT, while a registered buyer may deduct the corresponding input VAT subject to the applicable rules. Periodic VAT returns aggregate these liabilities and deductions, and the tax administration verifies whether the declared amounts are consistent with invoices, payments, customs information, and data reported by counterparties. Collection therefore depends not only on statutory rules, but also on the availability, timing, and verifiability of transaction information.
The overarching theoretical framework of this study is the economic theory of tax compliance and enforcement, applied through the concepts of information asymmetry, third-party reporting, and the self-enforcing properties of VAT. In the classical deterrence model, taxpayers weigh the expected benefit of under-reporting against the probability of detection and the resulting penalty (Allingham & Sandmo, 1972). Although originally developed in the context of income taxation, this logic is also relevant to VAT because the effective probability of detection depends on the information available to the tax administration and its capacity to verify reported transactions. When only the taxpayer observes a transaction, the administration faces an information disadvantage. Third-party records reduce this asymmetry because the seller’s output tax can be matched with the buyer’s input-tax claim. Kleven et al. (2011) show that non-compliance is substantially greater for self-reported income than for income subject to third-party reporting, illustrating how independently reported information constrains opportunities for under-reporting. Pomeranz (2015) demonstrates the importance of cross-checkable information within the VAT chain, while Naritomi (2019) shows that documentation incentives at the final transaction stage can strengthen reporting. More generally, Slemrod (2019) emphasises that enforcement effectiveness depends on information, detection probability, and administrative capacity.
Information technology can strengthen this mechanism at several stages: it can improve record creation within firms, standardise invoice data, accelerate transmission to the tax authority, automate cross-checking, and support risk-based audit selection. These functions should not be treated as equivalent. Within the theoretical framework, they represent two related but distinct channels: compliance facilitation and administrative enforcement. Internal digital records may reduce errors and compliance costs without changing the administration’s information set, whereas mandatory transaction reporting directly changes the timing and structure of information available for control. This distinction provides the theoretical basis for the two digitalisation channels examined below.
2.2. EU Regulatory Framework, Tax Reporting, and Comparative Research Gap
The common VAT system of the European Union is based on Council Directive 2006/112/EC, which harmonises the main rules governing taxable transactions, the tax base, the right to deduct input tax, invoicing, and VAT reporting (Council of the European Union, 2006). Although the Directive establishes a common legal framework, Member States retain a degree of discretion over administrative procedures and control mechanisms. Administrative cooperation and the exchange of information between national tax authorities are governed by Regulation (EU) No 904/2010, which provides the institutional framework for combating cross-border VAT fraud (Council of the European Union, 2010).
Directive 2014/55/EU represents an important step towards the standardisation of electronic invoicing. It establishes a European standard for electronic invoices in public procurement and supports greater semantic and technical interoperability between national systems (Council of the European Union, 2014). Its scope is primarily limited to transactions between businesses and public authorities. It does not introduce a general requirement for the real-time reporting of private-sector transactions for VAT purposes, but it provides part of the technical foundation on which broader electronic invoicing and digital reporting systems can be developed.
In the absence of an initially harmonised EU model, Member States introduced different national reporting regimes. These include electronic ledgers, VAT listings, SAF-T-based systems, mandatory electronic invoicing, the transmission of invoice data after issuance, and clearance models in which an invoice is validated before it can be issued. These systems differ in reporting frequency, taxpayer coverage, transaction scope, technical format, and legal effect (European Commission, Directorate-General for Taxation and Customs Union, 2022). The existence of an electronic reporting requirement is therefore not sufficient in itself to classify a national system as continuous transaction control.
The regulatory framework changed substantially with the adoption of the ‘VAT in the Digital Age’ package on 11 March 2025. The package comprises Directive (EU) 2025/516, which amends Directive 2006/112/EC; Regulation (EU) 2025/517, which modifies the rules on administrative cooperation; and Implementing Regulation (EU) 2025/518, which revises information requirements for certain VAT schemes (Council of the European Union, 2025a, 2025b, 2025c).
The new framework provides for the phased introduction of digital reporting requirements based on electronic invoicing. From 1 July 2030, the requirements will apply to intra-Community B2B transactions. Existing national real-time digital reporting systems introduced before 1 January 2024 must be aligned with the common EU standards by 1 January 2035. The reform is intended to improve the availability and exchange of transaction-level information while reducing the fragmentation created by different national requirements.
The ViDA package confirms that electronic invoicing is regarded not only as a means of reducing the administrative burden on businesses, but also as an information infrastructure for tax control. Directive (EU) 2025/516 provides for an assessment of the consequences of electronic invoicing and digital reporting for VAT collection, the VAT gap, and the administrative costs faced by taxpayers and tax authorities (Council of the European Union, 2025a). The distinction between business digitalisation and administrative reporting therefore has direct regulatory significance. It also has theoretical significance because the reporting obligation determines whether accounting data remain under the control of the firm or become timely and verifiable information available to the tax administration, thereby connecting digital accounting with the tax compliance and enforcement framework developed in Section 2.1.
Existing research provides substantial evidence that electronic invoicing and transaction-level reporting can improve the information available to tax administrations. Much of this evidence is based on individual national reforms or firm-level data, including Peru, Rwanda, Italy, and Hungary (Bellon et al., 2022, 2023; Kotsogiannis et al., 2025; Heinemann & Stiller, 2025; Ván et al., 2025). Comparative research for the EU remains limited, particularly with regard to the distinction between voluntarily adopted business technologies and mandatory systems that transmit data to tax administrations. Comparison is further complicated by differences in timing, taxpayer coverage, reporting frequency, technical design, and accompanying reforms.
The present study addresses this gap by comparing two distinct channels within a common EU framework: the voluntary use of cloud accounting by firms and the mandatory digital reporting of transactions to tax authorities. It examines whether the relationships between these channels and the VAT gap remain visible after economic development, tax structure, and government effectiveness are taken into account. The analysis therefore considers not only whether digitalisation is associated with VAT collection, but also whether that association depends on who receives and can verify the information generated.
2.3. Economic, Fiscal, and Institutional Determinants of the VAT Gap
The VAT compliance gap is defined as the difference between the VAT revenue that would theoretically be collected under full compliance with the legislation in force and the revenue actually received. In the European Commission’s methodology, the theoretical amount is represented by the VAT Total Tax Liability (VTTL), while the gap is expressed as a percentage of the VTTL. It should not be interpreted solely as a measure of tax fraud. It also includes revenue losses arising from tax evasion, insolvencies, reporting errors, late payments, and statistical or methodological adjustments in the estimation of the theoretical tax base (European Commission, Directorate-General for Taxation and Customs Union, 2025).
The VAT compliance gap should be distinguished from the VAT policy gap. The compliance gap reflects the difference between liabilities under the existing legislation and the revenue actually collected. The policy gap, by contrast, arises from the design of the VAT system, including reduced rates, exemptions, and restrictions of the tax base. This distinction is important because weak VAT revenue performance may result either from non-compliance or from the regulatory structure of the tax system (Cnossen, 2022). The present study focuses specifically on the VAT compliance gap and on the economic, institutional, and technological factors associated with revenue collection under the existing regulatory framework.
Early comparative empirical evidence illustrates the interaction between tax-system design and administrative capacity. Agha and Haughton (1996) find that VAT complexity, the number of rates, system maturity, and administrative resources help explain differences in compliance across countries. The study is retained as an early empirical benchmark rather than as the theoretical foundation of the present analysis; the information-based framework is developed in Section 2.1.
Studies of the European Union confirm the multifactorial nature of the VAT compliance gap. Zídková (2014) associates differences in the gap with the shadow economy, the structure of consumption, the level of economic development, and characteristics of the tax system. Majerová (2016) highlights the role of corruption and the broader institutional environment, while Pastusiak et al. (2022) identify economic growth and government effectiveness as important determinants of the VAT gap in the EU. Taken together, these studies indicate that higher income levels and stronger administrative institutions are generally associated with better VAT collection.
The method used to estimate the VAT gap also affects its interpretation. The European Commission’s official estimates are based on a macroeconomic top-down approach in which the theoretical VAT base is reconstructed using national accounts, tax revenue data, and information on final and intermediate consumption. Nerudová and Dobranschi (2019) propose an alternative stochastic tax frontier approach that distinguishes between a persistent country-specific component and a time-varying component of the gap. These methodological differences demonstrate that the VAT gap is an estimated rather than directly observed quantity. Its value may change following revisions to national accounts, tax revenue data, or the assumptions used to calculate the theoretical liability.
These considerations are particularly important when examining the relationship between digitalisation and VAT collection. Higher-income and better-governed countries generally have both a more digitalised business sector and more effective tax administrations. An observed negative correlation between digital technology adoption and the VAT gap does not therefore demonstrate an independent technological relationship. It may instead reflect broader differences in economic development, institutional quality, and enforcement capacity. Income and government effectiveness must consequently be taken into account when assessing whether different forms of digitalisation are independently associated with the VAT compliance gap. In the empirical models, economic development, tax structure, and government effectiveness are therefore included as controls for potentially confounding country characteristics, without interpreting their inclusion as establishing causal effects.
2.4. Voluntary Business Digitalisation and Cloud Accounting
The digital transformation of accounting is changing the way in which firms create, process, store, and use financial information. Cloud accounting refers to the provision of accounting software, computing resources, and data storage over the internet, usually in the form of a service that users access remotely. Unlike traditional on-premises systems, cloud-based solutions can provide a centralised database, automatic updates, real-time access to information, and closer interaction between firms and their accountants (Dimitriu & Matei, 2015).
The potential benefits include a reduction in the initial cost of information infrastructure, the automation of repetitive operations, the faster closing of accounting periods, and a decrease in some of the errors involved in manual data entry. The cloud architecture facilitates the integration of accounting systems with banking platforms, customer relationship management systems, e-commerce, and other sources of transaction information. This can enhance the timeliness, completeness, and traceability of accounting records and improve internal control (Moll & Yigitbasioglu, 2019; Mihai & Duțescu, 2022; Chipriyanova & Krasteva-Hristova, 2023).
From the standpoint of tax compliance, these features suggest several possible mechanisms. The automated recording of invoices and payments may reduce unintentional errors, assist in the correct determination of the tax base, and facilitate the timely submission of returns. The systematic storage of source documents may create a more reliable audit trail, while integration between individual business processes may make discrepancies between reported sales, purchases, and cash flows harder to sustain. In this sense, cloud accounting may indirectly encourage the formalisation of activity and compliance with tax obligations. This represents the compliance-facilitation channel identified within the theoretical framework developed in Section 2.1.
This mechanism nevertheless has significant limitations. First, the adoption of cloud systems is voluntary and is not evenly distributed across firms and countries. The decision to adopt the technology depends on firm size, financial and human resources, digital skills, perceived security, the regulatory environment, and the quality of the information infrastructure (Tawfik et al., 2023). Firms that use cloud accounting may already be more productive, more formalised, and more inclined to comply with legislation even before adopting it. The observed relationship between the technology and tax compliance may therefore reflect pre-existing characteristics of the firms.
Second, a cloud accounting system primarily improves the internal information environment of the firm. Its use alone does not mean that transaction data are automatically supplied to the tax administration, nor that they are submitted in a standardised format and can be matched against the information held by trading counterparties. A firm may maintain detailed digital records without the tax authority obtaining any more direct or more timely access to them than under traditional periodic reporting.
Third, technology may reduce unintentional errors, but it does not necessarily eliminate the deliberate concealment of transactions. When information remains under the control of the taxpayer and is not verified through an independent source, the scope for the incomplete reporting of sales or for the manipulation of accounting records does not disappear. The benefits of cloud accounting to the firm should not, therefore, be automatically equated with benefits to the tax administration.
The existing research on cloud accounting focuses mainly on adoption, cost savings, accounting-information quality, organisational readiness, and the changing role of accountants. A recent systematic review confirms that most studies examine benefits, challenges, adoption determinants, and organisational outcomes, with limited attention to tax administration or national compliance measures (Vo Van et al., 2025). Recent evidence also shows that adoption is conditional on perceived benefits, security concerns, organisational readiness, government support, and vendor support (Alshenaifi & El Sayad, 2026). Evidence on whether wider cloud-accounting adoption is independently associated with a lower country-level VAT gap therefore remains limited. Taken together, the literature supports an expected negative but conditional association: cloud accounting may facilitate accurate compliance, but its voluntary and selective adoption and its limited effect on the information available to the tax administration weaken the basis for expecting a direct causal relationship. These mechanisms and limitations are used in Section 2.6.1 to formulate the business-channel hypothesis.
2.5. Mandatory Digital Reporting and the Information Position of the Tax Administration
Administrative digitalisation differs from voluntary business digitalisation because it changes not only how firms process accounting information, but also how tax administrations receive and use transaction data. Under continuous transaction control systems, information from invoices or individual transactions is transmitted to the tax authority in real or near-real time. Depending on the national model, the administration may receive invoice data after issuance, validate selected information, or require prior clearance before an invoice acquires legal validity.
The theoretical basis of this mechanism lies in the informational structure of VAT. The tax creates a connected chain of sales, output tax, purchases, and deductible input tax. Information reported by the seller can therefore be compared with the input tax claimed by the buyer. Pomeranz (2015) shows that third-party information and the possibility of cross-checking strengthen the self-enforcing properties of VAT. The consequences are not limited to the firms directly audited, but may spread through the supply chain. Naritomi (2019) reaches a related conclusion for the final stage of the transaction chain, showing that encouraging consumers to request receipts increases the likelihood that sales are reported.
Mandatory digital reporting strengthens this information mechanism by reducing the period between the occurrence of a transaction and the receipt of the relevant data by the tax administration. Under traditional reporting systems, information is submitted periodically and often in an aggregated form. This creates a longer interval in which transactions may be concealed, modified, or omitted. The submission of structured transaction-level data allows invoices to be matched automatically, discrepancies to be detected more rapidly, and audits to be directed towards taxpayers presenting a higher compliance risk. This represents the administrative-enforcement channel identified in Section 2.1: mandatory reporting increases the timeliness and verifiability of information and can therefore raise the effective probability of detecting non-compliance without necessarily increasing the overall number of audits.
Empirical studies of national reforms support this information mechanism. Bellon et al. (2022) find that mandatory electronic invoicing in Peru increases reported sales, purchases, and VAT liabilities, while Bellon et al. (2023) show that effects may spread through supplier and customer networks. European evidence is also emerging. Heinemann and Stiller (2025) identify a reduction in cross-border VAT fraud following Italy’s mandatory e-invoicing reform, whereas Ván et al. (2025) show that Hungary’s online cash-register reform increased reported turnover, with effects varying by company size and with macroeconomic and concurrent-policy confounding requiring caution.
Evidence from Rwanda similarly indicates that electronic invoicing can improve the information available for tax control. Kotsogiannis et al. (2025) find that digital invoices support more precise audit targeting and are associated with higher net VAT payments. The administrative contribution of electronic invoicing therefore arises not only from the reporting of additional transactions, but also from the more efficient use of limited enforcement resources.
The systematic review by Hesami et al. (2024) concludes that electronic invoicing and pre-filled tax returns can reduce administrative costs and support compliance when they are accompanied by suitable institutional and technological infrastructure. More broadly, Okunogbe and Santoro (2023) emphasise that information technologies can assist tax administrations in identifying the tax base, facilitating compliance, and monitoring taxpayer behaviour. Their effectiveness nevertheless depends on the quality of the information generated and on the administration’s capacity to integrate that information into enforcement and taxpayer services.
At the European level, comparative evidence remains more limited. The European Commission’s assessment of digital reporting requirements distinguishes periodic transaction controls from continuous transaction controls and identifies substantial differences between national systems in terms of reporting frequency, taxpayer coverage, transaction scope, and data format (European Commission, Directorate-General for Taxation and Customs Union, 2022). Spain, Hungary, and Italy introduced different forms of continuous transaction control between 2017 and 2019, while Greece subsequently implemented the myDATA system through a phased process. Other Member States apply periodic transaction reporting, electronic ledgers, or SAF-T-based requirements that do not necessarily provide information in real or near-real time.
This diversity highlights the need to distinguish between electronic invoicing and mandatory digital reporting. An electronic invoice may be used only for the exchange of information between a seller and a buyer, without its data being transmitted automatically to the tax authority. In such cases, its function remains mainly operational and resembles voluntary business digitalisation. Under continuous transaction control, by contrast, the invoice or transaction record becomes a direct source of administrative information. The expected relationship with the VAT gap therefore depends not merely on the digital format of the document, but on the mandatory and timely transmission of structured data to the tax administration.
The presence of a reporting obligation does not guarantee the same outcome in every country. National regimes differ in their coverage, technical design, reporting deadlines, and enforcement intensity. Their effectiveness also depends on data quality, system interoperability, analytical capacity, and the subsequent use of the reported information. Incomplete coverage, frequent technical changes, and limited administrative capacity may weaken the relationship between digital reporting and VAT collection. The new systems may also impose initial costs on firms through software adaptation, staff training, and changes in internal accounting processes.
Despite these qualifications, mandatory digital reporting directly alters the information relationship between taxpayers and the state. It provides the tax administration with more timely and potentially verifiable information than voluntary business digitalisation alone. Taken together, the theoretical arguments and empirical evidence support an expected negative association between mandatory digital reporting and the VAT gap. Because the mechanism involves the direct transmission of transaction information to the tax administration, this relationship is expected to be more immediate than that of voluntary cloud accounting. Differences between national systems and the simultaneous introduction of other reforms nevertheless prevent the expected association from being interpreted automatically as a uniform causal effect. These mechanisms and identification limitations are used in Section 2.6.2 to formulate the administrative-channel hypothesis.
2.6. Hypotheses Development
The hypotheses synthesise the theoretical mechanisms and empirical evidence reviewed in the preceding sections. The theoretical framework explains how the two forms of digitalisation may influence tax compliance, while the country-level empirical analysis tests whether the expected relationships are observed after relevant economic, fiscal, and institutional factors are taken into account. Accordingly, the hypotheses concern associations with the VAT gap rather than causally identified effects.
2.6.1. Voluntary Cloud Accounting and the Business Channel
Cloud accounting can improve the completeness, timeliness, and traceability of accounting records and may reduce unintentional reporting errors. These benefits provide a reason to expect a negative association with the VAT gap. However, adoption is voluntary, selective, and mainly improves the firm’s internal information environment. The expected relationship is therefore empirical rather than assumed to be causal.
The empirical literature supports the individual components of this mechanism, although it does not establish a direct country-level relationship with the VAT gap. Existing studies associate cloud accounting with improvements in accounting-information quality, internal control, and reporting efficiency (Moll & Yigitbasioglu, 2019; Mihai & Duțescu, 2022; Chipriyanova & Krasteva-Hristova, 2023). At the same time, adoption depends on organisational readiness, digital skills, perceived security, government support, and vendor support (Tawfik et al., 2023; Vo Van et al., 2025; Alshenaifi & El Sayad, 2026). The literature therefore supports a plausible but conditional negative association, whose independence from economic development and institutional quality requires empirical examination.
Hypothesis 1 (H1).
The use of cloud accounting in firms is associated with a lower VAT gap.
2.6.2. Mandatory Digital Reporting and the Administrative Channel
Mandatory reporting differs because it supplies tax administrations with structured transaction information in real or near-real time. This can strengthen cross-checking, risk assessment, and audit targeting. The relationship may still be confounded by simultaneous reforms and institutional capacity, but the information mechanism implies a stronger expected association than for voluntary internal digitalisation.
The empirical evidence reviewed in Section 2.5 is consistent with this expectation. Studies of mandatory electronic invoicing and transaction-reporting reforms identify improvements in reported transactions, audit targeting, VAT payments, and the detection or reduction in tax fraud across different national settings (Bellon et al., 2022, 2023; Kotsogiannis et al., 2025; Heinemann & Stiller, 2025; Ván et al., 2025). Systematic and comparative research further indicates that these outcomes depend on data quality, institutional capacity, and the integration of reported information into enforcement processes (Hesami et al., 2024; Okunogbe & Santoro, 2023; European Commission, Directorate-General for Taxation and Customs Union, 2022). The evidence therefore supports the expected direction of the relationship, while differences in system design and concurrent reforms require caution in its causal interpretation.
Hypothesis 2 (H2).
Mandatory digital reporting of transactions is associated with a lower VAT gap.
2.6.3. Convergence in VAT Collection
Previous EU evidence shows that differences in the VAT gap are associated with economic development, tax-system characteristics, corruption, and government effectiveness (Zídková, 2014; Majerová, 2016; Pastusiak et al., 2022). The common EU regulatory framework, increasing administrative cooperation, and the diffusion of tax-control reforms may allow Member States with initially weaker collection performance to improve more rapidly. At the same time, countries that already have relatively low VAT gaps have less scope for further reductions. These considerations provide a basis for testing whether the differences between Member States have narrowed over time.
The descriptive evidence also indicates that Member States with initially high VAT gaps may have improved faster. Testing this pattern is relevant because convergence can coexist with multiple reform channels and should not be attributed automatically to digital reporting. The convergence hypothesis is therefore assessed separately from H1 and H2.
The resulting relationship is interpreted as evidence of a general catching-up process rather than as a causal effect of either digitalisation channel. It may reflect combinations of economic growth, institutional improvement, tax-administration reforms, and country-specific measures, as well as regression to the mean or revisions to the estimated VAT gap.
Hypothesis 3 (H3).
EU Member States with higher initial VAT gaps experience larger subsequent reductions, indicating beta-convergence.
3. Materials and Methods
3.1. Data and Variables
The empirical analysis is based on panel data for the 27 member states of the European Union over the period of 2013–2024. The dependent variable is the difference between the theoretically due and the actually collected VAT, referred to hereafter as the VAT gap. It represents the discrepancy between the theoretically due value added tax (VAT Total Tax Liability, VTTL) and the VAT revenue actually received, expressed as a percentage of the VTTL.
This indicator measures the share of potential revenue that is not collected owing to tax evasion, insolvency, reporting errors, technical corrections, or forms of tax optimisation. The data are drawn from the annual report of the European Commission’s Directorate-General for Taxation and Customs Union (European Commission, Directorate-General for Taxation and Customs Union, 2025). A single edition of the report is used, so as not to mix revised estimates from different years. For the main regression estimates, the sample is restricted to 2023 inclusive, since the values for 2024 are preliminary forecasts. The few negative values of the VAT gap—Ireland in 2021 and Luxembourg in the 2021–2022 period—arise mechanically when accrued receipts exceed the estimated theoretical liability and are retained as reported; setting them to zero leaves the results substantively unchanged.
The two digitalisation channels are measured separately. The business channel is proxied by the share of enterprises using cloud-based accounting software, drawn from Eurostat surveys on information and communication technologies in enterprises. This is a narrower measure than the overall degree of accounting digitalisation: it does not capture the number of modules used, intensity of use, integration with enterprise systems, or connection to tax-reporting interfaces. Comparable observations are not available for every year. Alternative indicators include the share of firms purchasing paid cloud services, the use of more sophisticated cloud services, and voluntary electronic invoicing.
The administrative channel is measured through a binary indicator for the presence of mandatory digital reporting of transactions in real or near-real time. These are continuous transaction control (CTC) systems, under which transaction information is submitted to the tax administration considerably earlier and in a more structured form than under traditional periodic reporting.
In order to separate any independent relationship between digitalisation and the VAT gap from the influence of accompanying factors, three control variables are included in the models. The first is gross domestic product per capita in purchasing power standards, which reflects the level of economic development. The second is the implicit tax rate on consumption, which characterises the tax structure. The third is the government effectiveness index from the World Bank’s Worldwide Governance Indicators, used as a measure of administrative and institutional capacity (World Bank, 2025). The definitions, units of measurement, and sources of all the variables are summarised in Table 1.
Table 1.
Variables, model roles, definitions and sources.
The panel is intentionally unbalanced and no missing values are imputed. Observation counts therefore vary across tables for three reasons. First, the descriptive statistics in Table 2 are computed over all assembled country-years for each variable, whereas the regressions are restricted to 2013–2023. Second, Eurostat does not report every business-digitalisation indicator for every country and year, and GDP per capita in purchasing power standards is available from 2016 onwards, which reduces the common estimation sample once controls are added. Third, lagging a variable removes the first available observation, and the sensitivity checks exclude particular years or countries. Each table reports the effective number of observations used.
Table 2.
Descriptive statistics.
Data preparation was carried out in Microsoft Excel 365, and preliminary data checks and descriptive analysis in IBM SPSS Statistics 29. All estimations and figures were produced in Python 3.11 (statsmodels, linearmodels, and matplotlib). The analytical workbook contains the assembled dataset, descriptive calculations, regression outputs, and chart data.
3.2. Coding of Mandatory Digital Reporting
The mandatory-reporting variable is a country-year binary treatment indicator. It equals 1 from the first calendar year in which a legally binding continuous transaction control regime applies to the relevant domestic transactions and 0 before that year. Classification requires mandatory transaction-level transmission to the tax administration in real or near-real time; voluntary e-invoicing, periodic summary reporting, and systems without direct administrative transmission are coded as 0. The dates and legal bases were checked against national legislation and EU comparative documentation. Over the main period, Spain is coded from 2017, Hungary from 2018, Italy from 2019, and Greece from 2021.
Because implementation may begin part-way through a year, an alternative coding uses the first full calendar year of operation. The baseline coding therefore captures the legal start year, whereas the alternative coding tests whether partial-year exposure affects the estimate. This is a timing sensitivity check, not a different definition of the policy.
Countries that apply periodic electronic reporting, but not real-time or near-real-time submission of transaction data, are not included in the group of countries with a CTC regime. This is the case for Portugal, which does not meet the definition of continuous transaction control used in the study. Romania introduces a similar regime in 2024, but remains outside the main estimation sample, which is restricted to 2023. The robustness of the results to its exclusion is nevertheless tested separately.
3.3. Empirical Strategy
The empirical strategy distinguishes the three hypotheses and preserves the percentage-point interpretation of the dependent variable. Standard errors are clustered at the country level. The business-channel models examine cross-country and within-country variation in voluntary adoption. The administrative-channel model is a staggered-adoption two-way fixed-effects difference-in-differences (TWFE DiD) specification that compares changes before and after CTC adoption while absorbing persistent country differences and common year shocks. The convergence equation is cross-sectional. Because these models answer different questions, they are reported separately.
Hypothesis 1 is first tested through stepwise pooled OLS, with controls added sequentially to show whether the cloud coefficient is sensitive to economic development and institutional quality. The baseline business-channel equation is:
where i indexes countries and t indexes years; VATGapit is the VAT compliance gap; α is the intercept; Cloudit is the share of enterprises using cloud accounting; β1 is its estimated coefficient; Xit is the vector of control variables; γ is the corresponding coefficient vector; and εit is the error term. The stepwise design is diagnostic: it shows whether the initial association survives the addition of variables that are correlated with both digital adoption and collection capacity.
VATGapit = α + β1Cloudit + γ′Xit + εit,
The business-channel sensitivity checks replace the focal measure, lag cloud adoption, use voluntary e-invoicing, and estimate a two-way fixed-effects model. The latter is written as:
where αi denotes country fixed effects; λt denotes year fixed effects; Digitalit is the focal business-digitalisation indicator used in the relevant specification; β2 is its estimated coefficient; Xit is the vector of control variables; γ is the corresponding coefficient vector; and εit is the idiosyncratic error term. Country effects absorb time-invariant national characteristics, while year effects absorb common EU shocks. Alternative measures, timing, and sample restrictions follow the sensitivity logic used in empirical digital-tax studies (Bellon et al., 2022; Heinemann & Stiller, 2025), while the results remain associational.
VATGapit = αi + λt + β2Digitalit + γ′Xit + εit,
Hypothesis 2 is examined first through an illustrative before-and-after comparison and then through a staggered-adoption TWFE DiD specification. The simple comparison provides descriptive scale and is not treated as a causal estimate.
The regression-based administrative-channel specification compares each country with its own pre-adoption level while accounting for common annual developments:
where CTCit is the binary mandatory-reporting indicator; δ is its estimated coefficient; αi and λt denote country and year fixed effects; Xit is the vector of controls; γ is the corresponding coefficient vector; and εit is the idiosyncratic error term. A causal TWFE DiD interpretation would require parallel untreated trends, no anticipatory response before the mandate, and no time-varying confounders correlated with adoption. These conditions are not established here: adoption is staggered, only four countries are treated, and the event-time profile shows a pre-adoption decline. Accordingly, δ is interpreted as an average conditional association rather than a causal treatment effect.
VATGapit = αi + λt + δCTCit + γ′Xit + εit,
Administrative-channel sensitivity checks add controls, use the first full implementation year, exclude the pandemic years, and exclude Romania. The event-time profile is a diagnostic of pre-adoption dynamics rather than a dynamic treatment-effect estimator. Recent staggered-treatment research shows why pre-trends and heterogeneous adoption timing require caution in causal interpretation (Callaway & Sant’Anna, 2021; Sun & Abraham, 2021).
The event-time profile arranges the mean VAT gap of the four adopting countries from four years before to two years after the mandate. Its purpose is to assess whether pre-adoption evolution is compatible with the parallel-trends assumption; it does not estimate causal dynamic effects. A decline before t = 0 indicates that broader administrative reforms, anticipation, or other country-specific developments may account for part of the subsequent improvement.
Hypothesis 3 is tested through the following beta-convergence equation:
where ΔVATGapi,2014–2023 is the percentage-point change in the VAT gap between 2014 and 2023; VATGapi,2014 is the initial VAT gap; GovEffi,2014 is initial government effectiveness; α is the intercept; ρ and θ are the estimated coefficients on the initial VAT gap and government effectiveness, respectively; and εi is the cross-sectional error term. A negative ρ indicates that countries with higher initial gaps subsequently record larger reductions. The uncontrolled model tests unconditional convergence, while the model with initial government effectiveness tests whether the pattern persists after accounting for initial institutional capacity.
ΔVATGapi,2014–2023 = α + ρVATGapi,2014 + θGovEffi,2014 + εi,
The implied annual speed of convergence is calculated as β = −ln(1 + ρ)/T, with a half-life of ln(2)/β, where T = 9 is the length of the period; the formula derives from the log-linear convergence model and is applied here as an approximation to the level specification, since zero and negative gap values preclude a logarithmic transformation.
4. Results
4.1. Descriptive Statistics and Dynamics
The VAT gap remains one of the significant problems facing the public finances of the European Union. In 2023, the member states fail to collect nearly €128 billion of the theoretically due value added tax. This represents around 9% of the total theoretically due VAT in the Union, against an average level of 12% over the observed period (Table 2). Behind this aggregate figure, however, considerable differences between the member states stand out. The distribution of the uncollected tax and its dynamics over time show that the problem cannot be explained through a single ‘average’ model. On the contrary, the data delineate progress, persistent structural differences, and renewed deterioration after the period of the sharpest narrowing of the VAT gap, all at the same time.
The first important result is the high heterogeneity between the member states (Table A1). In 2023, Luxembourg and Austria collect almost all of the theoretically due VAT, with the uncollected share standing at 0.2% and 1.0% respectively. At the other end of the distribution, Romania loses close to one-third of its theoretical receipts (30.0%), and Malta almost one-quarter (24.2%). Between these extreme values, a familiar structural pattern emerges: the southern and eastern member states are more often located at the high end of the distribution, whereas the western and Scandinavian economies are characterised by lower levels of uncollected VAT. The VAT gap is therefore not an evenly distributed problem across the EU, but rather a concentrated phenomenon whose weight is more strongly pronounced in a limited group of economies.
The dynamics over time initially show a clear improvement (Table 3). The average EU-27 VAT gap narrows from 15.7% of the theoretically due VAT in 2014 to 7.9% in 2021. In absolute terms, the aggregate amount of uncollected VAT in the Union falls from around €145 billion to €83 billion over seven years. After 2021, however, this downward trajectory is interrupted. The VAT gap rises again—to 9.3% in 2023 and 9.6% according to the preliminary estimate for 2024—with the uncollected sum returning to approximately €128 billion. This reversal shows that the progress achieved is not irreversible and raises the question of which factors actually contribute to the sustained narrowing of the VAT gap.
Table 3.
Year-by-year dynamics, EU-27 (cross-country averages).
The same period coincides with an accelerated digitalisation of the accounting function in firms. The share of firms using cloud accounting increases by almost fourfold—from 6.6% in 2014 to 26.0% in 2023 (Table 3). Here, however, substantial differences between the member states are observed. The Scandinavian economies have a clear advantage: Finland (56%), Sweden (54%), and Denmark (49%) are considerably further ahead than the rest of the Union. At the same time, in Bulgaria (6%), Greece (7%), and Romania (10%), the use of cloud accounting remains limited. Alongside the differences in VAT collection, a second, digital stratification between the member states thus emerges.
Cloud-accounting use expands while the VAT gap narrows, and the raw pooled correlation is negative (r = −0.37; Figure 1a). The wide dispersion around the fitted line shows that similar levels of cloud adoption coexist with very different VAT gaps, and the country-years under a continuous transaction control regime are not concentrated at the upper end of adoption. Figure 1b partials out income, tax structure, and government effectiveness from both variables; the slope is then indistinguishable from zero and the confidence band includes it. The unconditional relationship may therefore reflect country characteristics rather than an independent technological effect, a possibility examined formally in Section 4.3.
Figure 1.
The VAT gap and cloud accounting in the EU-27, 2014–2023. Panel (a) plots country-year observations with a fitted line; hollow markers denote country-years under a continuous transaction control regime. Panel (b) is an added-variable plot with ln GDP per capita in PPS, the implicit tax rate on consumption, and government effectiveness partialled out. In both panels, the grey shading around the fitted lines represents the 95% confidence bands. Source: DG TAXUD, Eurostat, and World Bank WGI (World Bank, 2025); authors’ calculations.
The narrowing of the VAT gap is accompanied by a certain convergence between the member states. The standard deviation falls from 10.3 percentage points in 2014 to 6.6 percentage points in 2023, which shows that some of the countries with initially higher levels of uncollected VAT have achieved a more substantial improvement. This convergence is an important result, but it also raises a further analytical question: through which channels does the catching-up of the lagging countries take place?
The present section outlines this empirical picture without assigning causal mechanisms. The decline and partial convergence of the VAT gap coincide with expanding business digitalisation, rising incomes, institutional change, and mandatory reporting in some Member States. Section 4.2 tests Hypothesis 3 on convergence, while Section 4.3 and Section 4.4 examine Hypotheses 1 and 2 for the voluntary and mandatory digitalisation channels.
4.2. Convergence Between the Member States (Hypothesis 3)
The convergence analysis is retained as contextual rather than causal evidence. It tests whether countries with larger initial VAT gaps—among which several later CTC adopters are located—were already catching up over 2014–2023. A negative coefficient on the initial gap indicates beta-convergence, but does not identify the digitalisation channel responsible. Figure 2 displays this relationship, with Member States identified by ISO country codes, a 95% confidence band, and the four later CTC adopters distinguished by colour.
Figure 2.
Beta-convergence of the VAT gap across EU Member States, 2014–2023. The horizontal axis shows the initial VAT gap in 2014 (% of VTTL) and the vertical axis the subsequent percentage-point change; the grey shading around the fitted line represents the 95% confidence band, and Member States are labelled with ISO country codes. Red markers denote the four Member States that later introduced a continuous transaction control regime (ES, HU, IT, and EL). Source: DG TAXUD; authors’ calculations.
The results support Hypothesis 3 and show statistically significant beta-convergence. The estimated coefficient on the initial level is −0.49 (SE = 0.076; p < 0.001; n = 27), and the model accounts for around 62% of the cross-country variation in the subsequent change. Each additional percentage point of uncollected VAT at the start of the period is associated with approximately half a percentage point larger subsequent reduction. The implied annual speed of convergence is about 7.4%, corresponding to a half-life of approximately nine years.
The pattern is most visible among high-gap countries such as Slovakia, Italy, Greece, Latvia, and Lithuania, which record reductions of approximately 14–19 percentage points, whereas several initially low-gap countries remained stable or recorded small increases (Figure 2 and Table A2). Two high-gap Member States depart from this pattern: Romania and Malta reduce their gaps by 10.6 and 6.9 percentage points respectively—less than their initial levels would predict—and they constitute the two largest positive residuals in the regression.
The coefficient remains similar for 2013–2023 (−0.50) and 2014–2021 (−0.46), and excluding Romania and Malta strengthens rather than weakens it (−0.67; R2 = 0.80), indicating that the result is not driven by the two highest initial values. After initial government effectiveness is included, the coefficient on the initial gap remains negative and significant (−0.40; p = 0.002), although this does not identify the effect of subsequent institutional improvements.
For the central research question, convergence shows that CTC adoption occurred within a broader EU catching-up process. Improvements also occurred among non-adopters, so Hypothesis 3 provides context for interpreting Hypothesis 2 rather than evidence that reporting mandates caused the overall convergence. Regression to the mean and measurement uncertainty in initial VAT-gap estimates also remain possible.
4.3. The Business Channel: Cloud Accounting (Hypothesis 1)
The first hypothesis tests whether the voluntary digitalisation of accounting in firms is associated with a lower VAT gap. In this section, the focus is on the use of cloud accounting by business. The main question is whether this form of digitalisation has an independent relationship with better VAT collection, or whether the observed relationship is explained by other factors, such as income and the quality of institutions.
To test this, the VAT gap, measured as a percentage of the VTTL, is regressed on the share of firms using cloud accounting. The control variables are added in sequence. This approach makes it possible to trace how the coefficient on cloud accounting changes when the income level is included in the model first, and then the quality of institutions as well. The results are presented in Table 4.
Table 4.
The VAT gap and cloud accounting–stepwise OLS.
The initial relationship between cloud accounting and the VAT gap is negative and statistically significant. In the model without control variables, the coefficient is −0.25 (p < 0.001). This means that each additional percentage point of firms using cloud accounting is associated with an approximately 0.25 percentage point lower VAT gap (Table 4, column 1). At first glance, this result supports Hypothesis 1.
The relationship weakens considerably, however, once the broader economic and institutional context is taken into account. After the inclusion of income, the coefficient falls to −0.11 (column 2). After government effectiveness is added, it drops to −0.03 and is no longer statistically significant (column 3). In the full specification, the coefficient is practically zero (+0.01; column 4). This means that the independent relationship between cloud accounting and the VAT gap disappears once income and institutional quality are accounted for.
The result for government effectiveness is particularly important. It remains strongly and statistically significantly associated with a lower VAT gap (−8.2; p < 0.01). This shows that the seemingly negative relationship between cloud accounting and uncollected VAT largely reflects the institutional context. The countries in which business more frequently uses cloud accounting systems are usually also countries with higher incomes and a more efficient administration. Better VAT collection cannot, therefore, be attributed directly to cloud accounting itself.
This conclusion is confirmed by the additional checks presented in Table 5. With a full set of control variables, none of the alternative specifications shows a robust and statistically significant negative effect. The broader indicator of paid-for cloud services use is practically zero. Cloud accounting lagged by one year is likewise not statistically significant. Voluntary electronic invoicing shows no independent relationship with a lower VAT gap. The two-way fixed-effects model, which exploits the changes within individual countries over time, also finds no significant effect.
Table 5.
H1 robustness alternative measures and within-country variation.
In one of the checks, using a narrower indicator of more sophisticated cloud services, the coefficient is even positive. This means that the direction is the opposite of that expected in Hypothesis 1. This result should not be interpreted as evidence that cloud services increase the VAT gap. Rather, it shows that the relationship is unstable and depends on the way in which digitalisation is measured. This further weakens the argument that voluntary business digitalisation in itself leads to better VAT collection.
In sum, Hypothesis 1 does not find empirical support. The use of cloud accounting is negatively related to the VAT gap only in the simplest model, without control variables. Once income and the quality of institutions are accounted for, this relationship disappears. Cloud accounting cannot, therefore, be regarded as an independent factor in reducing uncollected VAT in the EU.
This result is logical from the standpoint of the mechanism of impact. Cloud accounting facilitates the internal reporting of firms, reduces administrative costs, and improves the organisation of accounting information. It does not, however, automatically mean that the tax administration receives more, better-quality, or more timely data on transactions. If the information remains largely within the firm, the effect on tax control is limited.
The results therefore direct attention to the distinction between two different types of digitalisation. The first is voluntary business digitalisation, in which firms themselves choose to use digital accounting solutions. The second is administrative digitalisation, in which the state requires the digital reporting of transactions and obtains more direct access to data. The present subsection shows that the first channel is not sufficient to explain the narrowing of the VAT gap. The next subsection therefore examines the second channel—the mandatory digital reporting introduced by the tax administrations.
4.4. The Administrative Channel: Mandatory Digital Reporting (Hypothesis 2)
The second hypothesis tests whether the mandatory digital reporting of transactions in real or near-real time is associated with a lower VAT gap. Here the focus is on continuous transaction control systems, under which the tax administration obtains more direct and more timely access to information on the transactions carried out.
This channel differs substantially from the voluntary use of cloud accounting by business. Cloud accounting digitalises the internal reporting of the firm. Mandatory digital reporting, by contrast, changes the way in which information on transactions reaches the tax administration. The expected effect on VAT collection should therefore be more direct.
Only four Member States adopt a regime meeting the study’s CTC definition during the main period: Spain in 2017, Hungary in 2018, Italy in 2019, and Greece in 2021. The TWFE DiD-style specification compares each country with its pre-adoption level while accounting for common EU-year developments. The small treated group limits statistical power and makes the average coefficient potentially sensitive to the trajectory of any one adopter. Results are reported in Table 6 and Table A3.
Table 6.
The VAT gap and the mandatory digital reporting (CTC) mandate.
The simplest comparison is the ‘before and after’ comparison of the introduction of mandatory digital reporting (Table A3). For the four countries that introduce such a regime, the average VAT gap falls from 19.7% before the introduction to 10.8% after it. This represents a decline of 8.8 percentage points. This value cannot, however, be taken as the pure effect of the measure, because over the same period the gap also narrows in the EU as a whole. For the countries without such a regime, the decline is 3.4 percentage points. The simple difference between the two groups therefore shows an additional reduction of approximately 5.5 percentage points for the countries that have introduced mandatory digital reporting.
The TWFE specification yields an estimated coefficient of −4.24 percentage points (Table 6, column 1). This is a conditional within-country association relative to common year effects; it should not be read as the VAT gap that would necessarily have prevailed in the absence of the mandate.
The coefficient remains between approximately −3.7 and −4.4 percentage points after controls, alternative start-year coding, exclusion of the pandemic years, and exclusion of Romania. This stability supports the descriptive robustness of the association, but it does not overcome the limited treated sample or establish causality.
This is consistent with the logic of the measure: once the tax administration begins to receive more timely and more complete information on transactions, the scope for evading, delaying, or misreporting VAT diminishes.
The event-time profile raises a direct concern for causal interpretation. The mean VAT gap falls from 21.6% four years before adoption to 15.9% in the year immediately preceding it. This visible pre-treatment decline is not consistent with an unqualified parallel-trends assumption and may reflect anticipation, earlier reforms, or other country-specific developments.
With only four treated countries, the event-time evidence also has limited power and cannot establish a common counterfactual trend. Mandatory reporting is typically introduced alongside broader tax-administration modernisation. The coefficient is therefore best described as a stable average association for the observed adopters, not a uniform or externally generalisable causal effect.
Even with this caution, the result for Hypothesis 2 clearly differs from the result for Hypothesis 1. The voluntary use of cloud accounting by business shows no independent relationship with a lower VAT gap once income and the quality of institutions are accounted for. Mandatory digital reporting, by contrast, remains consistently associated with a lower VAT gap of around 3–4 percentage points.
This distinction is central to the present study. The data show that not every form of digitalisation matters equally for VAT collection. What appears to be more important is not the mere fact that firms use digital accounting solutions, but whether the tax administration obtains timely and structured access to information on transactions. The VAT gap therefore responds more strongly to the digitalisation that changes the information position of the state than to the digitalisation that remains largely an internal instrument of business.
Hypothesis 2 thus receives empirical support, albeit with the necessary caution in the causal interpretation. Mandatory digital reporting is associated with a lower VAT gap, but this result must be understood as part of a broader process of administrative modernisation. The systematic comparison between the business channel and the administrative channel is the subject of the next subsection.
4.5. The Two Channels Side by Side
In the previous two sections, the two channels of digitalisation were examined separately. When the results are set against each other, a clear difference emerges between them. This is expressed not only in the magnitude of the estimated effects, but also in their robustness when control variables are added and when different checks are applied.
For the business channel, the initial relationship between cloud accounting and the VAT gap appears to be negative. In the specification without control variables, each additional percentage point of firms using cloud accounting corresponds to around 0.25 percentage points lower VAT gap (Table 4, column 1). This relationship weakens, however, in the fuller specifications. After the income level is accounted for, the effect diminishes, and after government effectiveness is included, the coefficient comes practically close to zero and ceases to be statistically significant (Table 4, columns 3–4).
A similar result is observed for the other measures of business digitalisation as well-paid-for cloud services, cloud accounting lagged by one year, and voluntary electronic invoicing. None of these indicators, nor the model that traces the changes within individual countries, shows a robust independent relationship with a lower VAT gap (Table 5).
For the administrative channel, the result is different and considerably more stable. The introduction of mandatory digital reporting is associated with a reduction in the VAT gap of around 3.7 to 4.4 percentage points. More significantly, this estimate remains close in magnitude across all the checks applied—with and without control variables, under an alternative definition of the starting year, when the pandemic years 2020–2021 are excluded, and when Romania is excluded (Table 6).
The two channels therefore display different empirical robustness. The relationship between cloud accounting and the VAT gap is maintained only in the more limited specifications and disappears once income and the quality of institutions are accounted for. The relationship between mandatory digital reporting and a lower VAT gap, by contrast, remains relatively stable regardless of the method of checking.
5. Discussion
5.1. Main Results and Scholarly Contribution
Taken together, the results distinguish two information channels. The cloud-accounting association disappears after economic and institutional controls are added, whereas mandatory reporting retains a negative coefficient. The latter result is informative as a comparative association, but the four adopters, heterogeneous regimes, and pre-adoption decline rule out a uniform causal interpretation.
This distinction complements the existing literature, in which digitalisation is often treated as a single, general phenomenon. The results show that digital technology in itself does not constitute a sufficient mechanism for improving tax compliance. What matters is whether it creates information that remains an internal resource of the firm, or forms a standardised and promptly accessible information trail for the tax administration. The contribution of the study is thus not only empirical but also conceptual: it offers a distinction between technologies that improve the accounting processes within the firm and technologies that alter the information position of the tax authority.
The result is consistent with the more general theory of tax compliance, according to which the effectiveness of control depends on the availability of verifiable information, the probability of detecting discrepancies, and the administration’s ability to apply penalties and corrective action (Slemrod, 2019). Under VAT, this mechanism is particularly important, because the input tax credit creates an interdependence between the seller and the buyer. When the information from the two sides of a transaction can be matched, the scope for unilateral concealment or improper deduction is reduced.
The analysis further indicates that the VAT gap is associated with a broader set of economic, fiscal, and institutional conditions. Neither business digitalisation nor mandatory reporting can be considered in isolation from income, the tax structure, administrative capacity, and the quality of institutions. This accords with the conclusions of Agha and Haughton (1996), Zídková (2014), Majerová (2016), and Pastusiak et al. (2022), according to which the outcomes of the VAT system depend simultaneously on its regulatory design and on the state’s ability to administer the tax.
5.2. Voluntary Cloud Accounting and the Absence of a Statistically Detectable Independent Association
Hypothesis 1 is not supported in the fully controlled specifications: the cloud-accounting coefficient becomes statistically indistinguishable from zero once income and government effectiveness are included, and alternative business-digitalisation indicators yield the same general conclusion.
This result does not mean that cloud accounting is economically ineffective or immaterial to accounting-information quality. Cloud-based solutions can reduce infrastructure costs, automate document processing, improve access to data, and facilitate interaction between firms and accountants (Dimitriu & Matei, 2015; Moll & Yigitbasioglu, 2019). Recent research nevertheless shows that the cloud-accounting literature is concentrated on adoption and organisational outcomes rather than on tax-authority information or country-level compliance (Vo Van et al., 2025). Adoption itself is conditional on readiness, perceived benefits, security, government support, and vendor support (Tawfik et al., 2023; Alshenaifi & El Sayad, 2026).
The absence of an aggregate association is consistent with the information mechanism: voluntary cloud systems may improve internal records without transmitting standardised data to the tax authority. It also reflects a measurement limitation. The Eurostat indicator records only whether enterprises use cloud-based accounting software; it does not measure the breadth, intensity, integration, or tax-reporting connectivity of that use.
Selection further complicates interpretation. Cloud adoption is more common in higher-income economies and among firms with stronger resources, skills, and organisational readiness. The raw relationship may therefore capture a wider environment of economic and institutional modernisation rather than a separate cloud-software effect (Tawfik et al., 2023).
The voluntary e-invoicing result reinforces this distinction: a digital invoice is not equivalent to an administrative reporting record when transmission is optional, and the data are not automatically available for cross-checking. Cloud accounting may therefore facilitate compliance and future reporting obligations without substituting for the administrative information mechanism.
5.3. Mandatory Digital Reporting as an Information and Control Mechanism
The results are consistent with Hypothesis 2 as an association, not as a causal treatment estimate. The negative coefficient persists across the reported specifications, but only four countries adopt CTC regimes and statistical precision varies. The evidence therefore cannot establish a uniform effect across Member States.
The information-based mechanism remains plausible. Third-party reporting and transaction matching strengthen the self-enforcing properties of VAT (Pomeranz, 2015; Naritomi, 2019), while timely structured records can support automated cross-checking, risk profiling, and audit targeting.
National evidence is consistent with this mechanism: mandatory electronic invoicing increased reported tax bases in Peru (Bellon et al., 2022, 2023), while electronic invoicing improved audit targeting and net VAT payments in Rwanda (Kotsogiannis et al., 2025). These studies show how digital records can strengthen administration, but their settings and identification strategies differ from the present EU panel.
The four national regimes differ in coverage, timing, reporting frequency, taxpayer scope, and administrative capacity. Country fixed effects absorb time-invariant differences, but they do not allow the mandate coefficient to vary across institutional contexts or remove time-varying reforms. The reported coefficient is therefore an average across heterogeneous arrangements.
Policy adoption may also be endogenous. Governments with large VAT gaps, ongoing modernisation programmes, or strengthening enforcement capacity may be more likely to introduce mandatory reporting. The pre-adoption decline is consistent with this possibility and means that the coefficient may combine the mandate with earlier and concurrent reforms.
The comparison nevertheless remains informative: only the administrative channel retains a negative coefficient under the common controls. The appropriate conclusion is that timely, structured, and verifiable information is more closely associated with lower VAT gaps in the observed sample—not that the same mandate would produce the same causal effect everywhere.
5.4. Institutional Quality and Convergence of the VAT Gap
The strong negative association between government effectiveness and the VAT gap indicates that digital technologies operate within a broader institutional environment. This finding is consistent with EU evidence linking VAT-gap differences to institutional quality and administrative effectiveness (Zídková, 2014; Majerová, 2016; Pastusiak et al., 2022). It is also consistent with reform studies showing that digital tools are often introduced alongside wider administrative and fiscal changes, making institutional capacity essential for interpreting the observed outcome (Heinemann & Stiller, 2025; Ván et al., 2025). A reporting system may generate large volumes of data, but the fiscal result depends on the administration’s ability to validate, match, analyse, and act on those data.
This conclusion is consistent with the OECD’s Tax Administration 3.0 model, according to which tax obligations should gradually be integrated into the natural systems used by businesses and fulfilled closer to the moment at which the taxable event occurs. Such integration may reduce the administrative burden while also improving control. Its success, however, requires interoperability, reliable digital identification, appropriate data protection, and sufficient organisational and analytical capacity within the tax administration (OECD, 2020, 2025).
The convergence result is best read as background to the digitalisation analysis. High-gap countries generally improved faster, including several CTC adopters, but substantial reductions also occurred among non-adopters. Convergence therefore documents a wider catching-up process rather than the effect of a particular reporting regime.
That wider process may combine economic growth, formalisation, institutional strengthening, information exchange, and national anti-evasion measures. The present data cannot allocate the convergence among these mechanisms or determine whether the relationship with digital reporting differs across institutional contexts.
5.5. Implications for European Union Policy
The findings have direct relevance to the ‘VAT in the Digital Age’ package. Directive (EU) 2025/516 introduces the main changes to Directive 2006/112/EC concerning electronic invoicing and digital reporting. Regulation (EU) 2025/517 adapts the rules on administrative cooperation and the exchange of information, while Implementing Regulation (EU) 2025/518 amends the information requirements for certain VAT schemes (Council of the European Union, 2025a, 2025b, 2025c).
From 1 July 2030, the new digital reporting requirements will apply to intra-Community B2B transactions, with electronic invoicing forming the basis of the system. By 1 January 2035, existing national real-time digital reporting regimes must be aligned with the common EU standards. The results of the present study are consistent with the rationale underlying this reform. Mandatory administrative reporting shows a more stable negative association with the VAT gap than voluntary business digitalisation. This does not, however, establish that introducing a reporting obligation alone will produce the same outcome in every Member State.
Because the estimated relationship may differ with institutional capacity and regime design, ViDA implementation should be accompanied by readiness diagnostics, phased testing, and differentiated support. Administrations with limited analytical capacity may require investment in data quality, matching infrastructure, staff skills, and risk-analysis systems before reporting volumes increase. More mature systems can focus on semantic interoperability and cross-border use. EU evaluation should therefore report outcomes by institutional capacity, taxpayer coverage, and reporting architecture rather than relying only on an EU-wide average.
The effectiveness of mandatory digital reporting depends first on the structure and interoperability of the data. Incompatible formats, different semantic standards, and fragmented technical requirements may hinder cross-border matching and increase compliance costs. The standards developed under Directive 2014/55/EU on electronic invoicing in public procurement provide an important foundation, but they do not resolve all the technical and institutional challenges associated with VAT reporting (Council of the European Union, 2014).
Second, the reform should avoid the duplication of reporting obligations. If firms are required to provide the same information through electronic invoices, separate transaction registers, periodic statements, and traditional VAT returns, digitalisation may increase rather than reduce the administrative burden. Data submitted once in a reliable and structured format should, where possible, be reused by the administration for cross-checking, risk assessment, and the pre-filling of VAT returns.
Third, particular attention should be paid to small and medium-sized enterprises. Large firms may be able to absorb the costs of adapting their ERP and accounting systems, whereas software, training, and technical support may create a disproportionate burden for smaller businesses. Transitional periods, affordable software solutions, public reporting interfaces, and clear technical guidance may help to reduce these difficulties. Voluntary cloud accounting can play a complementary role by providing the technical infrastructure through which firms meet their reporting obligations more efficiently.
Fourth, the accumulation of detailed transaction data raises important questions concerning data protection, cybersecurity, and proportionate use. The requirements of Regulation (EU) 2016/679 should be integrated into the design of the reporting systems from the outset (Council of the European Union, 2016). Regulation (EU) 2025/517 also establishes the framework for processing and exchanging information through the future central VIES system (Council of the European Union, 2025c). Effective control therefore needs to be accompanied by clearly defined access rights, retention periods, audit trails, and safeguards against unauthorised use.
Fifth, the success of ViDA should not be assessed solely on the basis of whether electronic invoicing and digital reporting have been formally introduced. More informative indicators would include the share of transactions covered, the timeliness and quality of the submitted data, the number of automatically detected discrepancies, the targeting and yield of tax audits, the change in compliance costs, and the subsequent development of the VAT gap. Directive (EU) 2025/516 itself provides for an assessment of the consequences for VAT collection and the administrative costs faced by businesses and tax authorities (Council of the European Union, 2025a).
The policy implication is not that voluntary business digitalisation is unimportant. Cloud accounting and integrated business systems may reduce compliance costs and facilitate the submission of structured transaction data. Their contribution is therefore complementary. They provide part of the technical infrastructure needed for digital reporting, but they do not substitute for the administrative mechanism through which transaction information becomes available to and verifiable by the tax authorities.
5.6. Research Limitations and Recommendations for Future Research
The mandatory-reporting result is identified from only four adopting countries. This small treated group reduces statistical power, leaves the average coefficient sensitive to country-specific trajectories, and limits external validity. Spain, Hungary, Italy, and Greece also implemented different reporting architectures and did so in different institutional settings; the estimate should not be generalised mechanically to all Member States or to every form of digital reporting.
The identification strategy has further limitations. A causal TWFE DiD interpretation would require parallel untreated trends, no anticipation, and no adoption-related time-varying confounding. The event-time profile shows a substantial decline before the mandate, so the parallel-trends condition is not supported by the descriptive evidence. Adoption may also be endogenous: governments facing large VAT gaps or already undertaking administrative reforms may be more likely to introduce CTC systems. Country fixed effects remove time-invariant heterogeneity, but not concurrent policy changes, evolving enforcement capacity, or reverse causality.
Measurement and aggregation also constrain interpretation. The binary CTC indicator cannot capture taxpayer coverage, reporting frequency, enforcement intensity, interoperability, or technical quality. The Eurostat cloud-accounting indicator measures the share of enterprises using cloud-based accounting software rather than the broader degree or intensity of accounting digitalisation. EU countries differ in administrative capacity, tax culture, and digital maturity, while country-level averages conceal firm-, sector-, and region-specific responses. The panel is unbalanced, and the VAT gap is an estimated quantity that may be revised.
Future research should combine longer post-adoption panels with modern staggered-adoption estimators, matched or synthetic-control case studies, and explicit models of policy adoption. Richer coding should distinguish clearance, real-time reporting, SAF-T, taxpayer coverage, implementation intensity, and enforcement use. Effects should be estimated separately by institutional capacity, region, firm size, sector, and baseline compliance risk. Measures of business digitalisation should capture software intensity, module integration, audit-trail quality, and connection to tax-reporting interfaces. These extensions would provide stronger evidence on when digital reporting works, for whom, and under which administrative conditions.
6. Conclusions
This study examines the relationship between digitalisation and the VAT gap in the EU-27 by distinguishing between two channels: the voluntary adoption of cloud accounting by firms and the mandatory digital reporting of transactions to tax administrations. This distinction reflects a fundamental difference in the information generated by the two processes. Cloud accounting primarily improves the internal processing of business information, whereas mandatory reporting provides tax authorities with more timely, structured, and potentially verifiable transaction data.
The descriptive results show that the VAT gap narrowed considerably over most of the period analysed, although the improvement was not continuous. The average gap across the Member States fell from approximately 16% of the theoretically due VAT in 2014 to about 8% in 2021, before increasing to around 9% in 2023. The uncollected amount in 2023 was approximately €128 billion. Considerable differences between countries nevertheless remain. The convergence analysis indicates that countries with a higher initial VAT gap generally achieved a larger subsequent reduction. This finding should be interpreted cautiously, since part of the observed convergence may reflect regression to the mean or measurement uncertainty in the initial estimates.
The econometric results reveal a clear difference between the two digitalisation channels. The initially negative association between cloud accounting and the VAT gap weakens after income is included and becomes statistically insignificant once government effectiveness is taken into account. Similar results are obtained with alternative indicators of business digitalisation. Hypothesis 1 is therefore not supported in the fully controlled specifications. This does not imply that cloud accounting provides no benefits to firms or tax compliance. It indicates that no separate association with the national VAT gap can be identified after broader economic and institutional conditions are considered.
Mandatory digital reporting retains a negative coefficient across the reported specifications, with estimates of approximately 3.7–4.4 percentage points. This supports Hypothesis 2 as an empirical association. It does not establish a causal or generally transferable policy effect: only four countries adopt during the main period, their VAT gaps decline before adoption, and the mandates coincide with broader reforms and potentially endogenous policy choices.
The main contribution is to distinguish organisational digital capability from information directly accessible to tax administrations. Hypothesis 3 documents a broader convergence process, but serves as contextual evidence rather than an explanation of the reporting coefficient. The results therefore support careful comparative interpretation, explicit modelling of institutional capacity, and evaluation of reporting systems by their design and administrative use.
For ViDA, the findings support interoperable, timely, and verifiable reporting while cautioning against a one-size-fits-all expectation. Outcomes are likely to vary with regime coverage, data quality, institutional capacity, analytical use, and business compliance costs. Phased implementation, differentiated support, safeguards for small firms and personal data, and evaluation by institutional context are therefore as important as formal adoption.
The conclusions remain bounded by the limitations detailed in Section 5.6, especially the unbalanced panel, the small number of CTC adopters, heterogeneous national systems, pre-adoption trends, and the use of an estimated aggregate VAT-gap measure.
Author Contributions
Conceptualization, V.G. and R.K.-H.; methodology, V.G.; software, V.G.; validation, V.G. and R.K.-H.; formal analysis, V.G.; investigation, V.G. and R.K.-H.; resources, V.G.; data curation, V.G.; writing—original draft preparation, V.G. and R.K.-H.; writing—review and editing, V.G. and R.K.-H.; visualization, V.G.; supervision, V.G. and R.K.-H.; project administration, V.G.; funding acquisition, V.G. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
This study is based entirely on publicly available secondary data. The VAT gap estimates are drawn from the European Commission, Directorate-General for Taxation and Customs Union (DG TAXUD), VAT Gap in the EU—2025 Edition. The indicators of business digitalisation and economic development are obtained from Eurostat, namely cloud accounting and paid cloud services (isoc_cicce_use), voluntary e-invoicing (isoc_eb_ics) and GDP per capita in purchasing power standards (nama_10_pc). The implicit tax rate on consumption is taken from DG TAXUD, Taxation Trends in the European Union (tax_itr), and government effectiveness from the World Bank Worldwide Governance Indicators (World Bank, 2025). The binary indicator of mandatory continuous transaction controls (CTC) was coded by the authors on the basis of national legislation. The compiled country–year panel and the accompanying coding of the CTC mandate are available from the corresponding author upon reasonable request.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
| CTC | Continuous Transaction Controls |
| DG TAXUD | Directorate-General for Taxation and Customs Union |
| DiD | Difference-in-Differences |
| EU | European Union |
| GDP | Gross Domestic Product |
| ITR | Implicit Tax Rate (on consumption) |
| OLS | Ordinary Least Squares |
| PPS | Purchasing Power Standard |
| VAT | Value Added Tax |
| ViDA | VAT in the Digital Age |
| VTTL | VAT Total Tax Liability |
| WGI | Worldwide Governance Indicators |
Appendix A
Table A1.
VAT gap and cloud accounting by country.
Table A2.
Beta-convergence of the VAT gap, 2014–2023.
Table A3.
The VAT gap before and after the CTC mandate.
References
- Agha, A., & Haughton, J. (1996). Designing VAT systems: Some efficiency considerations. The Review of Economics and Statistics, 78, 303–308. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Allingham, M. G., & Sandmo, A. (1972). Income tax evasion: A theoretical analysis. Journal of Public Economics, 1, 323–338. [Google Scholar] [CrossRef] [Scilit]
- Alshenaifi, Z., & El Sayad, S. (2026). Adoption of cloud-based accounting solutions in micro, small and medium-sized enterprises: Insights from the Kingdom of Saudi Arabia. Journal of Science and Technology Policy Management, 17(7), 1507–1528. [Google Scholar] [CrossRef] [Scilit]
- Bellon, M., Dabla-Norris, E., & Khalid, S. (2023). Technology and tax compliance spillovers: Evidence from a VAT e-invoicing reform in Peru. Journal of Economic Behavior & Organization, 212, 756–777. [Google Scholar] [CrossRef] [Scilit]
- Bellon, M., Dabla-Norris, E., Khalid, S., & Lima, F. (2022). Digitalization to improve tax compliance: Evidence from VAT e-invoicing in Peru. Journal of Public Economics, 210, 104661. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Callaway, B., & Sant’Anna, P. H. C. (2021). Difference-in-differences with multiple time periods. Journal of Econometrics, 225, 200–230. [Google Scholar] [CrossRef] [Scilit]
- Chipriyanova, G., & Krasteva-Hristova, R. (2023). Technological aspects of accounting automation system as a decision support system. Environment. Technology. Resources. Proceedings of the International Scientific and Practical Conference, 2, 28–33. [Google Scholar] [CrossRef] [Scilit]
- Cnossen, S. (2022). The C-inefficiency of the EU-VAT and what can be done about it. International Tax and Public Finance, 29, 215–236. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Council of the European Union. (2006). Council Directive 2006/112/EC of 28 November 2006 on the common system of value added tax. Official Journal of the European Union, L 347, 1–118. Available online: https://eur-lex.europa.eu/eli/dir/2006/112/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2010). Council Regulation (EU) No 904/2010 of 7 October 2010 on administrative cooperation and combating fraud in the field of value added tax (recast). Official Journal of the European Union, L 268, 1–18. Available online: https://eur-lex.europa.eu/eli/reg/2010/904/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2014). Directive 2014/55/EU of the European parliament and of the council of 16 April 2014 on electronic invoicing in public procurement. Official Journal of the European Union, L 133, 1–11. Available online: https://eur-lex.europa.eu/eli/dir/2014/55/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2016). Regulation (EU) 2016/679 of the European Parliament and of the Council of 27 April 2016 on the protection of natural persons with regard to the processing of personal data and on the free movement of such data. Official Journal of the European Union, L 119, 1–88. Available online: https://eur-lex.europa.eu/eli/reg/2016/679/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2025a). Council Directive (EU) 2025/516 of 11 March 2025 amending Directive 2006/112/EC as regards VAT rules for the digital age. Official Journal of the European Union, L 2025/516. Available online: https://eur-lex.europa.eu/eli/dir/2025/516/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2025b). Council Implementing Regulation (EU) 2025/518 of 11 March 2025 amending Implementing Regulation (EU) No 282/2011 as regards information requirements for certain VAT schemes. Official Journal of the European Union, L 2025/518. Available online: https://eur-lex.europa.eu/eli/reg_impl/2025/518/oj/eng (accessed on 20 June 2026).
- Council of the European Union. (2025c). Council Regulation (EU) 2025/517 of 11 March 2025 amending Regulation (EU) No 904/2010 as regards the VAT administrative cooperation arrangements needed for the digital age. Official Journal of the European Union, L 2025/517. Available online: https://eur-lex.europa.eu/eli/reg/2025/517/oj/eng (accessed on 20 June 2026).
- Dimitriu, O., & Matei, M. (2015). Cloud accounting: A new business model in a challenging context. Procedia Economics and Finance, 32, 665–671. [Google Scholar] [CrossRef] [Scilit]
- European Commission, Directorate-General for Taxation and Customs Union. (2022). VAT in the digital age: Final report, volume 1—Digital reporting requirements. Publications Office of the European Union. Available online: https://taxation-customs.ec.europa.eu/system/files/2022-12/VAT%20in%20the%20Digital%20Age_Final%20Report%20Volume%201.pdf (accessed on 20 June 2026).
- European Commission, Directorate-General for Taxation and Customs Union. (2025). VAT gap in the EU (2025th ed.). Publications Office of the European Union. [Google Scholar] [CrossRef]
- Heinemann, M., & Stiller, W. (2025). Digitalization and cross-border tax fraud: Evidence from e-invoicing in Italy. International Tax and Public Finance, 32, 195–237. [Google Scholar] [CrossRef] [Scilit]
- Hesami, S., Jenkins, H., & Jenkins, G. P. (2024). Digital transformation of tax administration and compliance: A systematic literature review on e-invoicing and prefilled returns. Digital Government: Research and Practice, 5, 1–20. [Google Scholar] [CrossRef] [Scilit]
- Kleven, H. J., Knudsen, M. B., Kreiner, C. T., Pedersen, S., & Saez, E. (2011). Unwilling or unable to cheat? Evidence from a tax audit experiment in Denmark. Econometrica, 79, 651–692. [Google Scholar] [CrossRef] [Scilit]
- Kotsogiannis, C., Salvadori, L., Karangwa, J., & Murasi, I. (2025). E-invoicing, tax audits and VAT compliance. Journal of Development Economics, 172, 103403. [Google Scholar] [CrossRef] [Scilit]
- Majerová, I. (2016). The impact of some variables on the VAT gap in the member states of the European Union. Oeconomia Copernicana, 7, 339–355. [Google Scholar] [CrossRef] [Scilit]
- Mihai, M. S., & Duțescu, A. (2022). How cloud accounting and integrated services based on AI can impact accounting companies? Proceedings of the International Conference on Business Excellence, 16, 849–858. [Google Scholar] [CrossRef] [Scilit]
- Moll, J., & Yigitbasioglu, O. (2019). The role of internet-related technologies in shaping the work of accountants: New directions for accounting research. The British Accounting Review, 51, 100833. [Google Scholar] [CrossRef] [Scilit]
- Naritomi, J. (2019). Consumers as tax auditors. American Economic Review, 109, 3031–3072. [Google Scholar] [CrossRef] [Scilit]
- Nerudová, D., & Dobranschi, M. (2019). Alternative method to measure the VAT gap in the EU: Stochastic tax frontier model approach. PLoS ONE, 14, e0211317. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- OECD. (2020). Tax administration 3.0: The digital transformation of tax administration. OECD Publishing. [Google Scholar] [CrossRef] [Scilit]
- OECD. (2025). Tax administration digitalisation and digital transformation initiatives. OECD Publishing. [Google Scholar] [CrossRef] [Scilit]
- Okunogbe, O., & Santoro, F. (2023). The promise and limitations of information technology for tax mobilization. The World Bank Research Observer, 38, 295–324. [Google Scholar] [CrossRef] [Scilit]
- Pastusiak, R., Bolek, M., & Pluskota, A. (2022). VAT gap determinants in the European Union. Studia Prawno-Ekonomiczne, 123, 119–132. [Google Scholar] [CrossRef] [Scilit]
- Pomeranz, D. (2015). No taxation without information: Deterrence and self-enforcement in the value added tax. American Economic Review, 105, 2539–2569. [Google Scholar] [CrossRef] [Scilit]
- Slemrod, J. (2019). Tax compliance and enforcement. Journal of Economic Literature, 57, 904–954. [Google Scholar] [CrossRef] [Scilit]
- Sun, L., & Abraham, S. (2021). Estimating dynamic treatment effects in event studies with heterogeneous treatment effects. Journal of Econometrics, 225, 175–199. [Google Scholar] [CrossRef] [Scilit]
- Tawfik, O. I., Durrah, O., Hussainey, K., & Elmaasrawy, H. E. (2023). Factors influencing the implementation of cloud accounting: Evidence from small and medium enterprises in Oman. Journal of Science and Technology Policy Management, 14, 859–884. [Google Scholar] [CrossRef] [Scilit]
- Ván, B., Lovics, G., Tóth, C. G., & Szőke, K. (2025). Digitalization against tax evasion: Evidence on the role of company size. Journal of Business Economics, 95, 749–776. [Google Scholar] [CrossRef] [Scilit]
- Vo Van, H., Abu Afifa, M., Nguyen, N., & Bui, D. V. (2025). Cloud accounting: A systematic literature review. Global Knowledge, Memory and Communication. Advance online publication. [Google Scholar] [CrossRef] [Scilit]
- World Bank. (2025). Worldwide governance indicators, 2025 revision [dataset]. Available online: https://www.worldbank.org/en/publication/worldwide-governance-indicators (accessed on 20 June 2026).
- Zídková, H. (2014). Determinants of VAT gap in EU. Prague Economic Papers, 23, 514–530. [Google Scholar] [CrossRef] [Scilit]
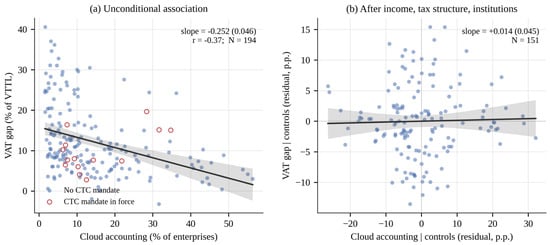
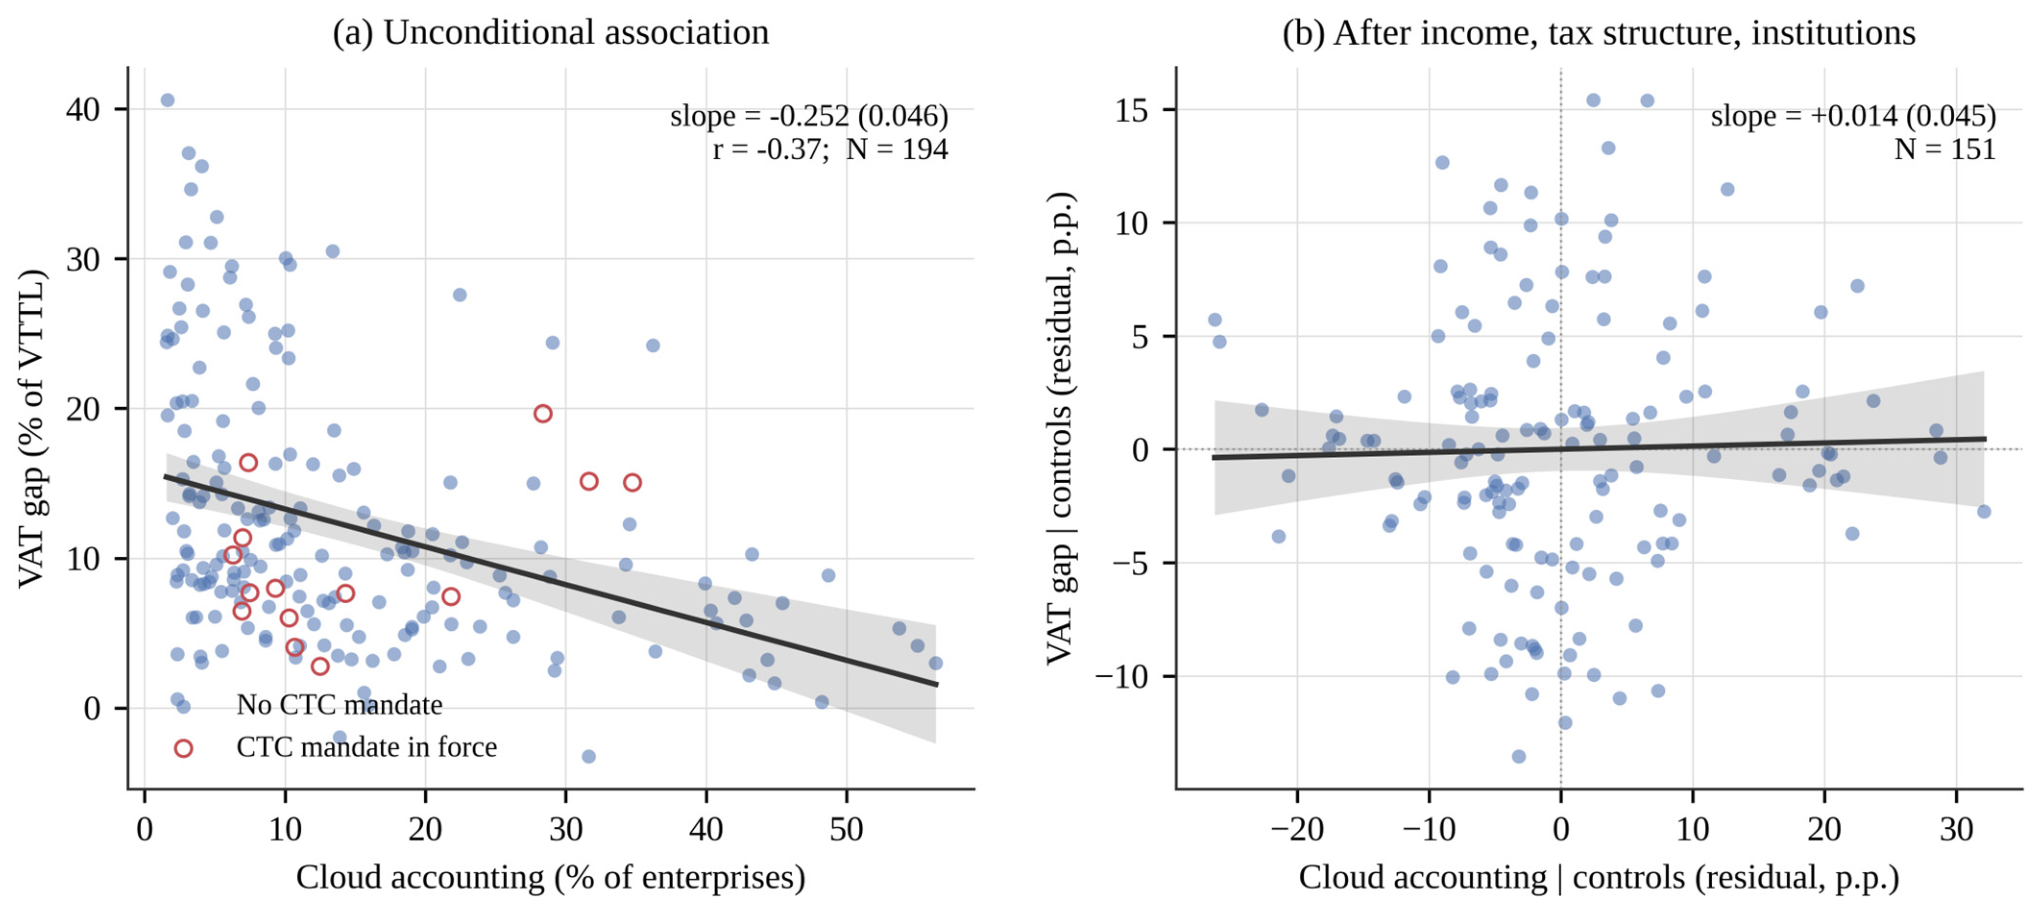
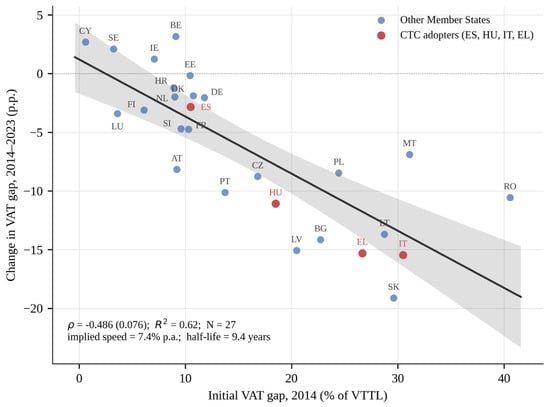
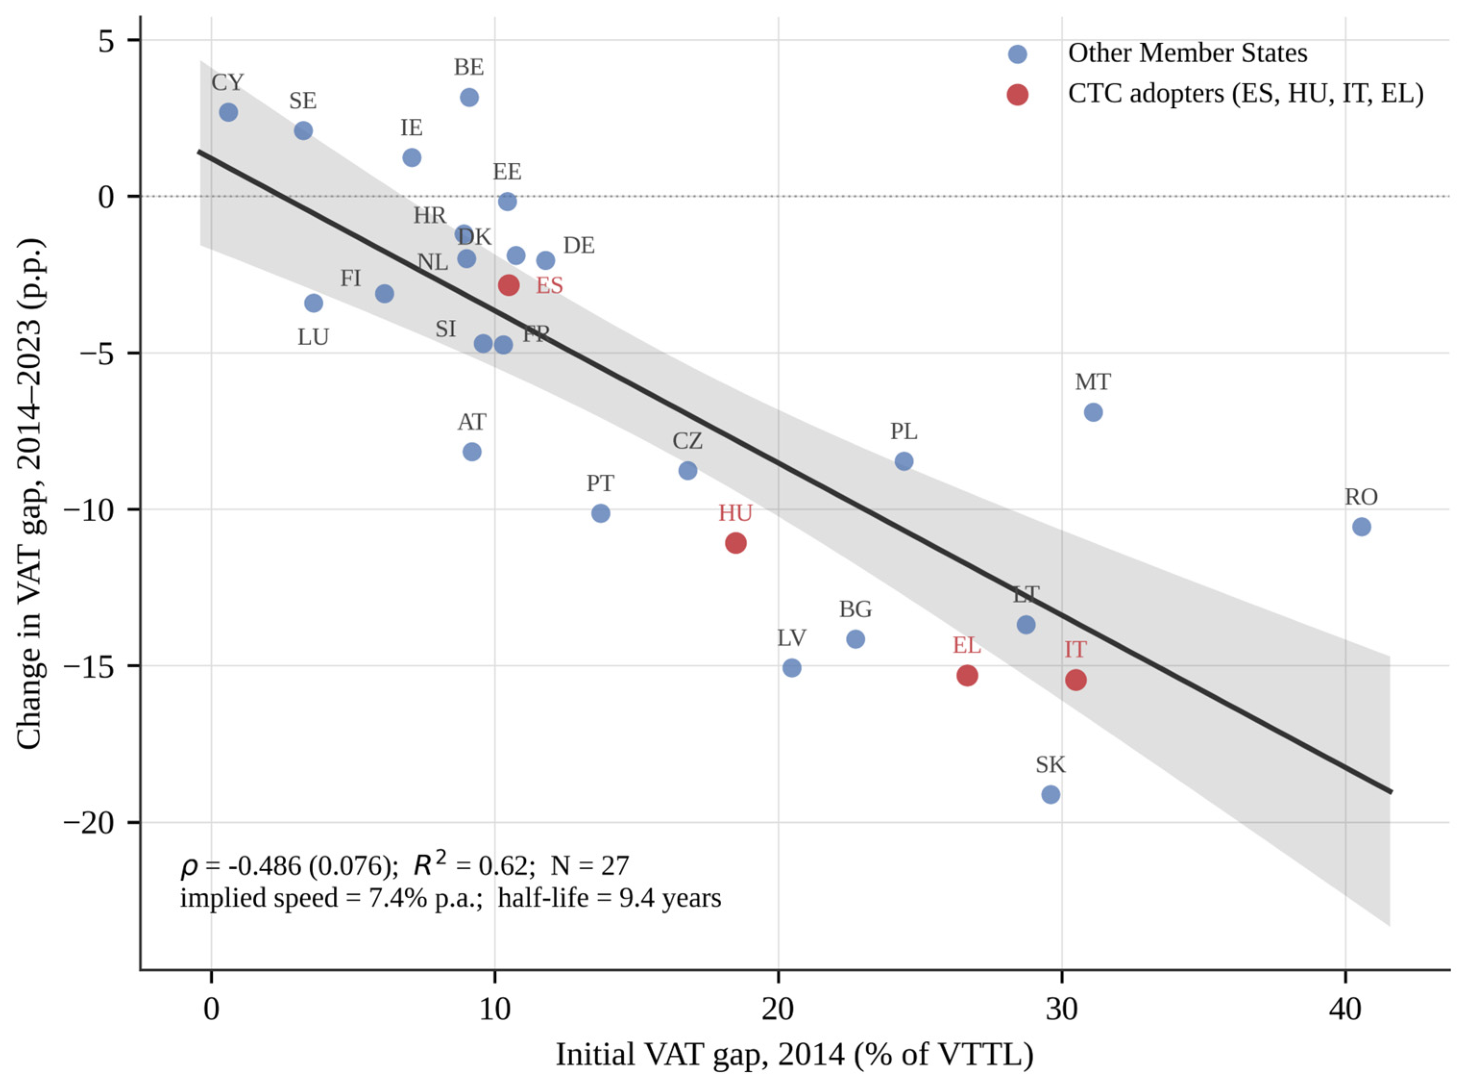

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.